
Free written scope consultation - allowances, timeline, and change-order rules on paper before a single trade is scheduled
Styles & brands we work with
- Kitchen remodeling
- Bathroom remodeling
- Home additions & ADU
- Roofing
- Windows & doors
- Driveway & pavers
- Fence
See the difference
 Before
 After
 Before
 After
 Before
 After
Do Impact Windows Lower Insurance in Mesquite, NV? Yes, But Only With the Right Paperwork
Yes, impact windows can lower your homeowner’s insurance in Mesquite, but not automatically. Nevada isn’t a wind-mitigation credit state like Florida, where insurers are required to give discounts for impact-rated products. Here, any credit is carrier-discretionary, and it usually hinges on documentation your insurer can actually verify: a product approval number, a contractor-signed installation certificate, and sometimes a third-party inspection report. If that paper trail isn’t in the right format at the time of install, you’ve paid for impact glass and gotten zero premium relief. Call (888) 413-6358 to talk through what your carrier needs before any order is placed.
That documentation gap is where most projects fall apart. We’ve seen it repeatedly in Mesquite: a homeowner buys impact-rated units from a distributor who offers a spec sheet and a handshake, the install wraps up, and six months later the insurer asks for a signed installation certificate that nobody can produce. The windows are fine. The discount isn’t there.
Why Nevada Discounts Work Differently Than Florida’s
In Florida, insurers are legally required to offer wind-mitigation credits, and the state publishes standardized forms. Nevada has no equivalent mandate. That means the discount you get here depends entirely on your specific carrier’s underwriting guidelines. Some national carriers offer an optional endorsement for impact-rated glazing. Others don’t credit it at all. A few will ask about wind-loss classification, which is where the conversation gets interesting for Mesquite properties.
The practical takeaway: don’t assume a discount exists. Call your insurer before you commit to a scope. Ask three specific questions:
- Does your policy offer any credit or endorsement for impact-rated windows, and what’s the current premium reduction?
- What documentation do you require to process the credit: product approval number, installation certificate, third-party inspection, or all three?
- Does the credit depend on a wind-loss classification for the property, and if so, how is that classification determined?
Get the answers in writing. Insurers change underwriting criteria, and what one rep says on the phone in spring may not match what the claims or underwriting department asks for in fall.
The Documentation Chain That Actually Satisfies an Insurer
Here’s what a complete insurance submission packet typically looks like. These are the items that show up again and again in carrier requirements, and each one needs to exist before the project closes.
1. Product Approval or Test Report
The window unit itself needs documented certification. That’s usually a Notice of Acceptance (NOA) or an equivalent ASTM E1886/E1996 test report showing the product met impact and cyclic pressure standards. Brand matters here. Andersen and Marvin impact-rated units carry documented design pressure (DP) ratings and published test certifications. Generic units from local distributors sometimes come with nothing more than a spec sheet, and a spec sheet without a test certification typically won’t qualify.
2. Signed Installation Certificate
Insurers want proof the units were installed correctly, not just that they were manufactured to standard. That means a certificate signed by a licensed contractor, tied to a specific permit number and address. This is where a permit record becomes valuable. In Mesquite, windows and doors on a residential structure require a Clark County permit and a final inspection sign-off. The permit number and inspection record become part of the submission packet.
3. Manufacturer’s Product Data Sheet
Less exciting but often required: the manufacturer’s published data sheet for the specific model and glass package. Having it assembled and matched to the certificate saves a round of back-and-forth with underwriting.
What Groundwork Assembles at Project Closeout
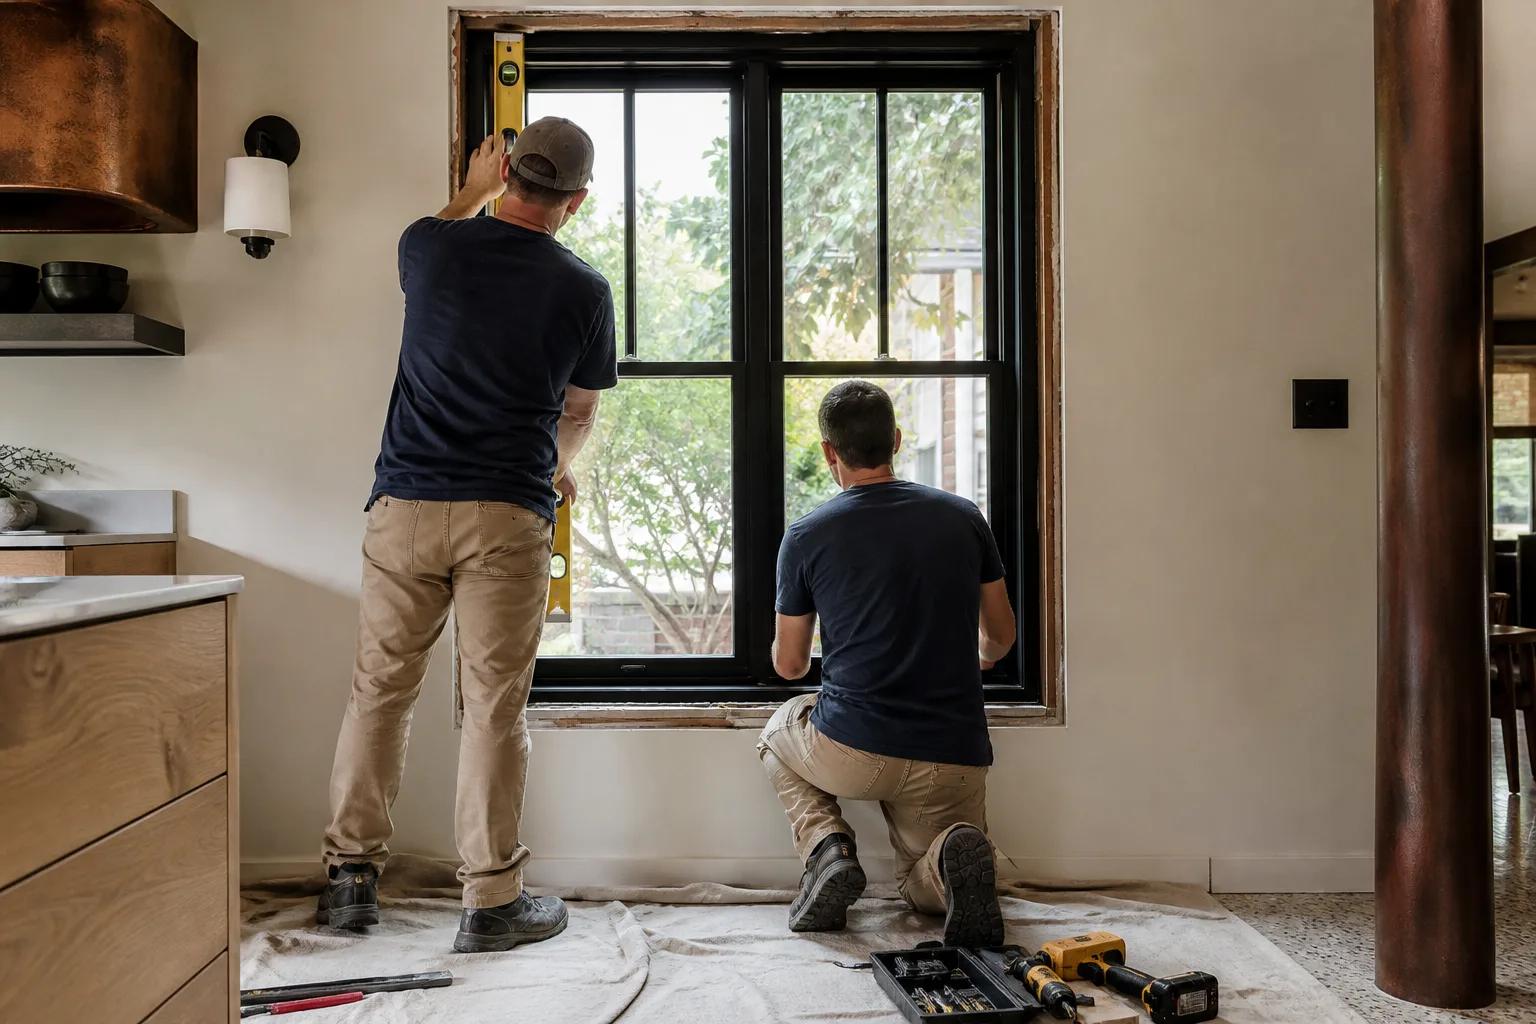
When we install Windows & Doors in Mesquite, the insurance submission packet comes together as part of closeout, not as an afterthought. That includes:
- The manufacturer’s NOA or ASTM E1886/E1996 test documentation for each unit installed
- Our signed installation certificate with the licensed contractor’s signature
- The Clark County permit record and final inspection sign-off
- The manufacturer’s product data sheets, matched to model and glass package
- A summary cover sheet listing the product approval numbers so underwriting doesn’t have to hunt for them
The alternative requires a third-party inspection report, which some carriers request anyway for anything beyond a straightforward replacement. If that’s the case, we’ll tell you before the project starts so you can build it into the timeline.
That paper trail also has a long tail. The 730-Day Done Right Promise and the permit record together create verifiable documentation years after installation, which matters if a carrier audits a policy or a new insurer asks for proof when you’re shopping. A cash-only crew with no permit record can’t produce any of that.
Why Mesquite’s Wind Exposure May Work in Your Favor
The Virgin River gorge funnels wind through Mesquite in ways that standard desert properties don’t experience. Some carriers classify properties by wind-loss history and exposure, and properties in the gorge corridor may qualify for a higher credit tier than a flat desert site would. That’s not a promise. It’s a question worth asking your carrier before the scope gets finalized, because if a wind-loss classification applies, it changes the math on the whole project.
Mesquite’s housing stock adds another wrinkle. The older stucco-on-frame homes in golf-course communities like Sun City and Highland Hills often have original windows from the 1980s to 2000s, which is exactly the age where older units fail airborne water and pressure testing. Newer custom builds and townhomes from the 2010s and 2020s may already have impact-rated glazing. Knowing which category your house falls into is the first step, and it’s usually a fifteen-minute inspection.
What Impact Window Installation Costs in Mesquite
Impact window installation in Mesquite runs $8,000-$25,000 for a typical whole-home scope. Standard window replacement runs $4,500-$15,000. The premium for impact-rated units covers glass, frame, and labor, and it’s the same whether the install produces a qualifying packet or not. That’s the argument for choosing a certified brand product: the cost is nearly identical, but the documentation is what turns a premium into a premium-plus-a-discount.
| Project Type | Price Range |
|---|---|
| Impact Window Installation | $8,000-$25,000 |
| Standard Window Replacement | $4,500-$15,000 |
| Roof Replacement (often bundled with window jobs in older homes) | $8,000-$20,000 |
| Roof Repair (often needed before window certification on older stock) | $400-$1,800 |
Roof and window projects often get bundled on the 1980s-to-2000s housing stock, because insurers reviewing a wind-loss credit sometimes want to see the envelope is intact. Not always, but often enough that we flag it during the first walkthrough instead of after.
FAQs
They can, but only through carrier-discretionary endorsements. Nevada does not mandate wind-mitigation credits the way Florida does, so the discount depends on your specific insurer’s underwriting guidelines, your property’s wind-loss classification, and whether you can produce the required documentation. Call your carrier before you buy and ask what they credit and what they require.
Most commonly three items: the window’s NOA or ASTM E1886/E1996 test report, a signed installation certificate from a licensed contractor tied to a permit, and the manufacturer’s product data sheet. Some carriers add a third-party inspection report. Assembling all four before the project closes is what makes the credit actually process.
Because they carry published DP ratings and test certifications that insurers recognize. A local distributor’s unit may perform just as well, but if there’s no documented certification, there’s no product approval number, and without that number there’s usually no credit. The cost between the two options is close; the documentation isn’t.
It can. Properties in the Virgin River gorge corridor sometimes qualify for a wind-loss classification that unlocks a higher credit tier than standard desert properties. Ask your carrier directly whether a classification applies to your address before the scope is finalized, because it changes the numbers on the whole project.
Get the Paperwork Right the First Time
If you’d rather have your windows assessed before committing to a scope, Groundwork Construction Co. of Mesquite offers a no-pressure walkthrough. We’ll look at your existing glazing, talk through what your carrier will likely require, and outline the documentation we’d assemble at closeout. Free estimate, upfront pricing, and financing options available. Call (888) 413-6358 or start at our Mesquite service area page for more on how projects run here.
Written by the team at Groundwork Construction Co. of Mesquite, serving Mesquite, NV.


